HOA and Condo Water Damage: Who Is Responsible in California?
The most administratively complicated water losses we handle. The technical work is routine; the boundary question is what goes wrong.
In most California associations the master policy covers the building structure and common elements, and your HO-6 policy covers everything inward from the walls plus your belongings. Where the failed component sat relative to the boundary in your CC&Rs decides who pays. Start mitigation immediately regardless — responsibility is settled afterwards, from documentation.
Mission Viejo has a great deal of attached housing under association governance — Canyon Villas, Palmia, parts of Casta del Sol, and townhome and condominium communities across the surrounding cities.
When water crosses a boundary in one of those buildings, the restoration is straightforward and the paperwork is not. Three or four parties, several policies, and one question that determines all of it: exactly what failed, and exactly where.
This is general information. Your governing documents control, and specific disputes warrant advice from a California attorney.
The boundary question
Every condominium and townhome community defines a boundary between the separate interest — what the owner owns — and the common area, which the association maintains. That definition is in the CC&Rs and it varies considerably between communities.
Broadly, the association typically maintains building structure, roof, exterior, and building systems serving more than one unit. The owner typically owns interior finishes, improvements, fixtures and contents. Many communities also define an "exclusive use common area" category for things like balconies and patios, where maintenance and repair duties can be split.
Water damage cuts straight across these boundaries, because water travels through the assemblies where the boundary sits.
The two policies, and the gap between them
The association carries a master policy covering the common area and, depending on how it is written, the original building improvements within units. Individual owners carry HO-6 policies covering their improvements, personal property, liability and loss assessment.
The gap between the two is where most disputes live, and the master policy deductible is the sharpest edge of it. Many associations carry substantial deductibles — sometimes larger than a modest loss — and where governing documents allow, that deductible can be allocated to the owner whose unit was involved.
Practically, that means smaller losses are frequently absorbed by owners through their HO-6 policies regardless of who was responsible. Knowing your association’s deductible figure before you need it is genuinely worth doing.
Common scenarios and how they usually break down
| What failed | Usually engages |
|---|---|
| Supply line inside a demising wall serving multiple units | Association / master policy |
| Angle stop or fixture inside one unit | That owner and their HO-6; liability to neighbours possible |
| Roof leak into a top-floor unit | Association for the roof; owner for interior improvements |
| Drain stack serving several units | Association / master policy |
| Appliance failure inside a unit | That owner; contents and improvements |
| Common-area irrigation flooding a ground-floor unit | Association, with owner’s policy for interior |
| Balcony or exclusive-use area drainage | Depends on CC&Rs — frequently split |
When the roof leaks and the damage lands inside your unit
This is the split we are asked to explain most often in South Orange County, because the two halves sit on opposite sides of the boundary. The roof is almost always a common element the association maintains. The drywall, insulation, flooring and belongings the water ruins on its way through are almost always yours.
So the association repairs the roof, and your HO-6 policy generally responds to the interior — even though you did nothing wrong and the failure was not yours. Owners find that counter-intuitive, and it is where most of these disputes start.
What shifts it is negligence. If the association knew the roof was failing, was told in writing, and did not act, the interior damage may become its liability rather than yours. That is exactly why the written record matters more than the conversation: a maintenance request logged eight months ago changes the analysis completely, and a phone call nobody minuted does not.
Who owns the pipes inside the walls
The usual rule in California condominium documents is that pipes serving a single unit are that owner’s responsibility, and pipes serving more than one unit are the association’s — regardless of which wall they happen to run through. A branch line feeding only your bathroom is usually yours even where it sits inside a common wall. The vertical stack carrying four units is usually the association’s even where it passes through your closet.
Your CC&Rs can define it differently, and some do. That is why the honest answer to "who pays" always starts with reading the governing documents rather than assuming the default rule applies to your building.
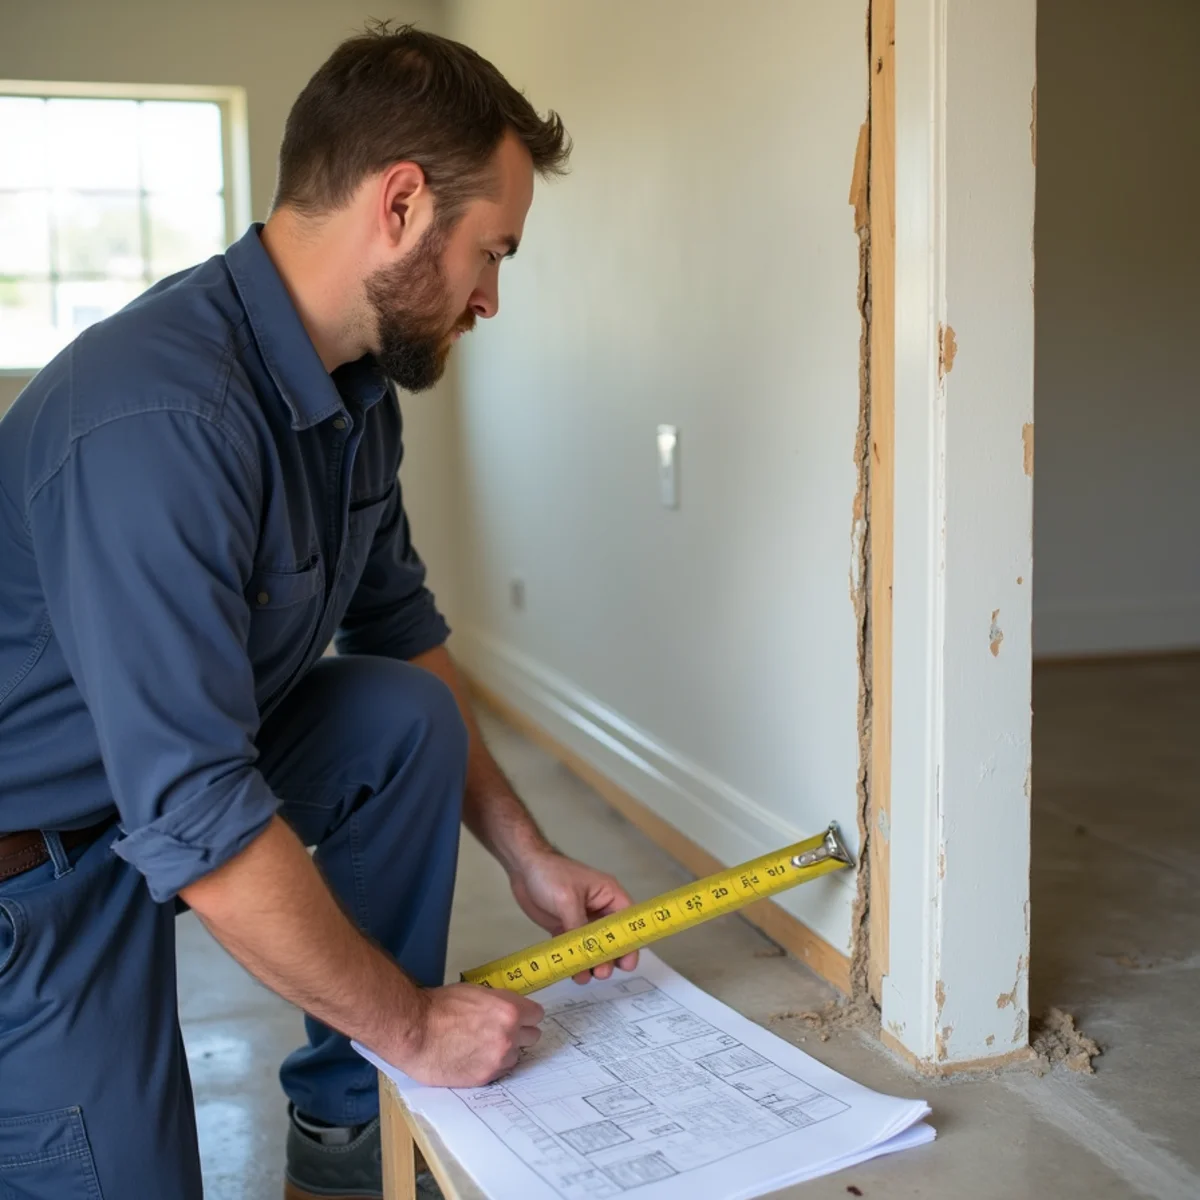
Practically, this is the reason we photograph the failed component in place before anything is removed. Whether a fitting served one unit or four is the entire basis of the responsibility question — and once the pipe is out of the wall and into a skip, nobody can prove which it was.
What to do in the first hour, as an owner
- Photograph and video everything before anything moves.
- Notify the association in writing immediately — email, not a phone call to a gate.
- Notify your own insurer.
- Call for mitigation. Do not wait for a responsibility determination. Every policy expects you to act to prevent further damage, and delay can prejudice your own claim.
- If the water came from a neighbouring unit, notify that owner in writing as well.
- Keep a written log of every conversation with dates, names and what was agreed.
What makes these resolve cleanly
Evidence, produced before anything is disturbed. The failure point photographed in place. The flow path documented from source to affected areas. Moisture mapping establishing extent across unit boundaries. Water category and class with reasoning. And a scope written so that each party can see their own exposure separately.
Given that, each carrier can apply the governing documents to a set of agreed facts. Without it, everyone argues about what happened, which takes months and satisfies nobody.
It is also why one contractor working across affected units is dramatically better than two working either side of a shared assembly. The same crew that documented the source dries both sides and rebuilds both sides, on one consistent record.
For boards and managers
- Know your master policy deductible and how your CC&Rs allocate it. Communicate it to members before an incident, not after.
- Have a restoration contractor identified in advance with access arrangements agreed, so an out-of-hours event is dispatch-and-go.
- Encourage members to carry adequate HO-6 cover including loss assessment.
- Maintain common-area plumbing and irrigation proactively; those failures generate the most contentious claims.
- Keep maintenance records. They matter enormously when a loss is questioned as a maintenance failure.
- Respond quickly to reports of soggy ground, damp common walls and unexplained wet patches. Those are the early signs.
Frequently asked
Why do water damage claims get denied?
The most common reason by far is that the loss is judged gradual rather than sudden — a slow leak that ran for months is excluded under most policies, while the same pipe bursting is covered. After that: water entering from outside the building, which needs separate flood cover; missing documentation of the condition before mitigation started; and delay, where a carrier argues the damage worsened because nobody acted promptly. Note the date you first noticed anything, in writing, on the day you notice it.
What water damage is not covered by insurance in California?
Standard California homeowners and HO-6 policies generally exclude gradual leaks and seepage, damage attributed to deferred maintenance, surface and flood water entering from outside, and in many cases sewer or drain backup unless a specific endorsement has been added. That backup endorsement is inexpensive and a great many condo owners do not have it — it is worth checking which way yours reads before you need it rather than after.
Does my condo policy cover damage I caused to a neighbour’s unit?
Usually yes, through the liability portion of your HO-6, where the damage resulted from something you are responsible for — a failed supply line to your own appliance being the common example. It is one of the better reasons to carry an HO-6 even where the master policy looks comprehensive. Many owners also hold loss assessment coverage they are unaware of, which can respond when an association levies its deductible across the membership.
Water came from the unit above. Do I claim on my policy or theirs?
Start with your own, and start mitigation immediately. Recovery between carriers happens afterwards through subrogation, and your neighbour’s liability depends on whether the failure resulted from their negligence — a component simply failing is often nobody’s fault. Do not let that question delay drying your home.
The association says it is my responsibility. Can I challenge it?
Yes, and it turns on the governing documents applied to the documented facts. Get the CC&R provisions the association is relying on in writing, and make sure the failure point and flow path were properly documented. If it remains disputed, a California attorney experienced in common interest developments is the right next call.
Can one contractor work across several units?
Yes, and it is by far the better approach. One crew, one consistent record, and no arguments about what was removed on which side of a shared assembly. We scope and invoice separately by unit so each party and carrier has clean documentation.
Expert insight
Do not wait for the association
The most damaging thing an owner can do is wait for the HOA and the neighbouring unit to agree who is at fault before anyone dries anything. Every policy expects you to act promptly to prevent further damage, and delay can prejudice your own claim. In the attached housing we work in around Mission Viejo, two or three lost days routinely turns a dryable loss into a demolition scope.
The bottom line
Document before you disturb, notify in writing, mitigate immediately, and settle responsibility afterwards from evidence rather than argument.
We handle attached-housing losses across Mission Viejo’s association communities regularly, and we produce the boundary documentation every party will eventually ask for.